If your salary finishes before the month does, you are not alone. Prices in Pakistan were 10.3% higher in September 2026 than a year earlier, according to the Pakistan Bureau of Statistics. Transport alone rose more than 27%. That means a Rs 1,00,000 salary today buys roughly what Rs 90,700 bought last year.
You cannot control petrol or electricity prices. You can control what happens to your salary in the first three days after it lands. This guide shows a plan that works on a normal Pakistani income, with real numbers.
Step 1: Save first, spend after
Most people try to save whatever is left at the end of the month. Usually nothing is left. Flip it around. On salary day, move your savings to a separate account before you pay anything else, then live on the rest.
A simple split that fits most families here:
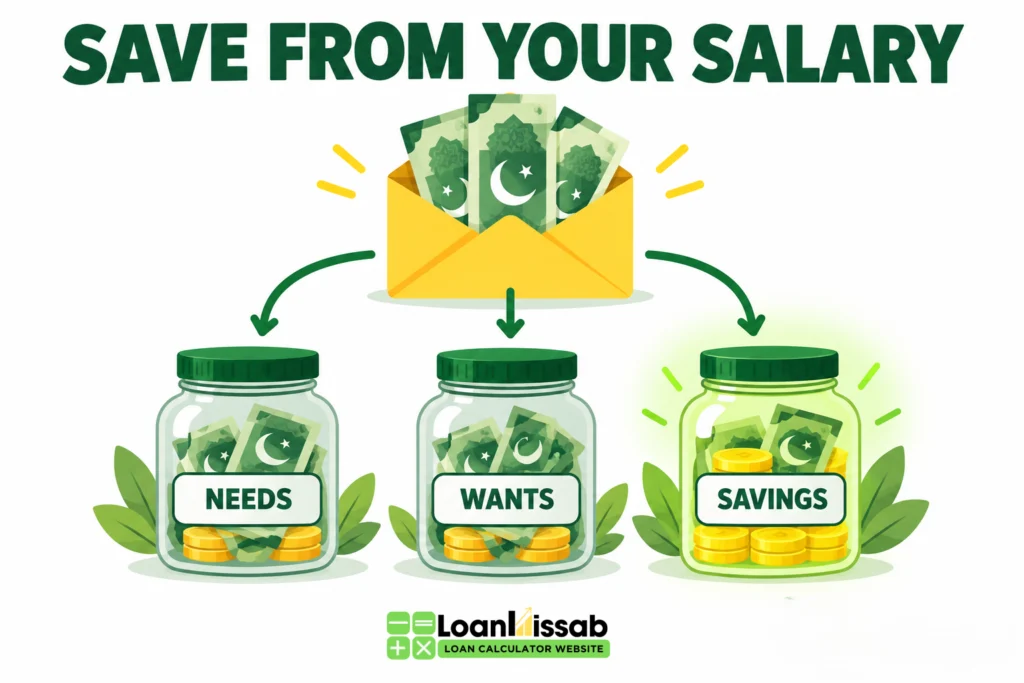
- 60 percent for needs: rent, bills, groceries, school fees, petrol, loan installments
- 25 percent for wants: eating out, clothes, gifts, weddings, mobile packages
- 15 percent for savings: paid to yourself first, every month
If 15 percent feels impossible, start with 5 percent and add 1 percent every two months. The habit matters more than the amount.
What this looks like on real salaries
The tax figures below use the salaried slabs for tax year 2027 (July 2026 to June 2027), as passed in the federal budget.
| Monthly salary | Income tax a month | Save each month | Needs | Wants |
|---|---|---|---|---|
| Rs 50,000 | Rs 0 | Rs 5,000 (10%) | Rs 32,500 | Rs 12,500 |
| Rs 80,000 | Rs 300 | Rs 12,000 (15%) | Rs 47,800 | Rs 19,900 |
| Rs 1,50,000 | Rs 6,000 | Rs 30,000 (20%) | Rs 82,000 | Rs 32,000 |
On a higher salary, push savings above 15 percent. Your needs do not double when your pay doubles, so the extra should go to savings.
Step 2: Build an emergency fund before anything else
Your first goal is three months of expenses kept somewhere you can reach in a day. For an Rs 80,000 earner that is around Rs 2 lakh. This money is for a job loss, a hospital bill or a car repair, so you never have to take an expensive loan in a hurry.
Keep it in a savings account or a short term National Savings certificate, not in gold or property, because you may need it quickly.
Step 3: Make your savings earn more than inflation
Cash under the mattress loses about 10% of its value a year right now. Committees (BC) are a great discipline tool, but they pay no profit, so after a year your money buys less than when you started.
From 1 October 2026, National Savings pays 11.80% on Defence Savings Certificates and 12.72% on Behbood certificates (Behbood is only for people over 60, widows and disabled persons). Tax is deducted from the profit at source: 15% if you are on the FBR Active Taxpayers List, 30% if you are not. So becoming a filer is one of the easiest ways to earn more.
To see how it adds up: Rs 10,000 a month for five years, with profit reinvested at about 10% after tax, grows to roughly Rs 7.7 lakh. You put in Rs 6 lakh. The rest is profit.
We compare all your options in where to invest your savings in Pakistan.
Step 4: Keep loans under a third of your pay
Banks may approve installments up to about half of your income. That does not mean you should take them. If car, bike and personal loan installments together stay under a third of your take home pay, you can still save every month.
Before you sign anything, put the numbers into our personal loan calculator or car loan calculator and check the monthly figure against your budget. Our guide on how much salary you need for a loan explains how banks decide.
Already paying a loan? Read should you pay off your loan early to see whether extra savings should go to the bank first.
Step 5: Cut the leaks you do not notice
- Petrol: at Rs 382 a litre, an Alto driven 40 km a day uses about Rs 25,000 of fuel a month. Car pooling twice a week can save Rs 7,000. See what your car really costs to run.
- Electricity: check which slab you are in on your bill. Staying under 200 units in summer can cut the bill sharply.
- Subscriptions and packages: cancel anything you have not used in a month.
- Shopping on credit card: if you cannot clear it in full, the profit rate is far higher than any saving can earn.
Step 6: Plan big costs a year early
Weddings, Eid, school admissions and a motorcycle are not surprises. Divide the cost by twelve and save that amount every month in a separate pocket. You will pay cash instead of taking a loan, or at least borrow much less.
A month by month checklist
- On salary day, move your savings first.
- Pay bills and installments in the first week.
- Write down every spend above Rs 1,000 for one month. You will be surprised.
- Every three months, raise your savings by 1 percent.
- Every year, put the full raise or bonus aside before it disappears into daily life.
Saving on a Pakistani salary is not about earning more first. It is about deciding where each rupee goes before the month decides for you.
This guide is for general information and is not financial advice. Rates checked on 21 October 2026.
Related calculators and guides
- Petrol Price History in Pakistan 2018 to 2026: From Rs 81 to Rs 382 a Litre
- Petrol Up 45% in a Year: 6 Warning Signs Every Pakistani Driver Should Know
- Solar Panels on Installments in 2026: Is It Still Worth It After Net Billing?
- Bank Loan Calculators